
Introducing EQX: Tokenized U.S. Spot Equities on Hyperliquid
文章目录
Introducing EQX: tokenized U.S. stocks and ETFs issued natively on HyperCore as HIP-1 tokens. Our first 11 markets will soon open for 24/7 trading on @HyperliquidX’s public order book.
EQX tokenized equities at a glance:
-
Tradable permissionlessly 24/7 on Hyperliquid’s order book
-
Backed 1:1 by shares (and only shares) held at DTC-connected custodians
-
No issuer-added fees (pay only Hyperliquid’s standard spot trading fee)
-
Dividends that compound automatically, and voting instructions via onchain signature
Traders deserve clear answers about what they hold: who issues the token, where the shares are held, what it costs and what protections they have. Too often, issuers bury or obfuscate these details. Today, we’re releasing our website and public docs so anyone can examine how EQX works before trading begins.
We’re committed to delivering the best tokenized spot equity offering legally possible, so that Hyperliquid can become the primary venue for price discovery of U.S. equities over time. A tokenized equity is only as good as the structure behind it and we’ve built EQX around real share backing, clear holder protections and zero issuer fees. Here’s how those pieces fit together.
Issuance, share backing and holder rights
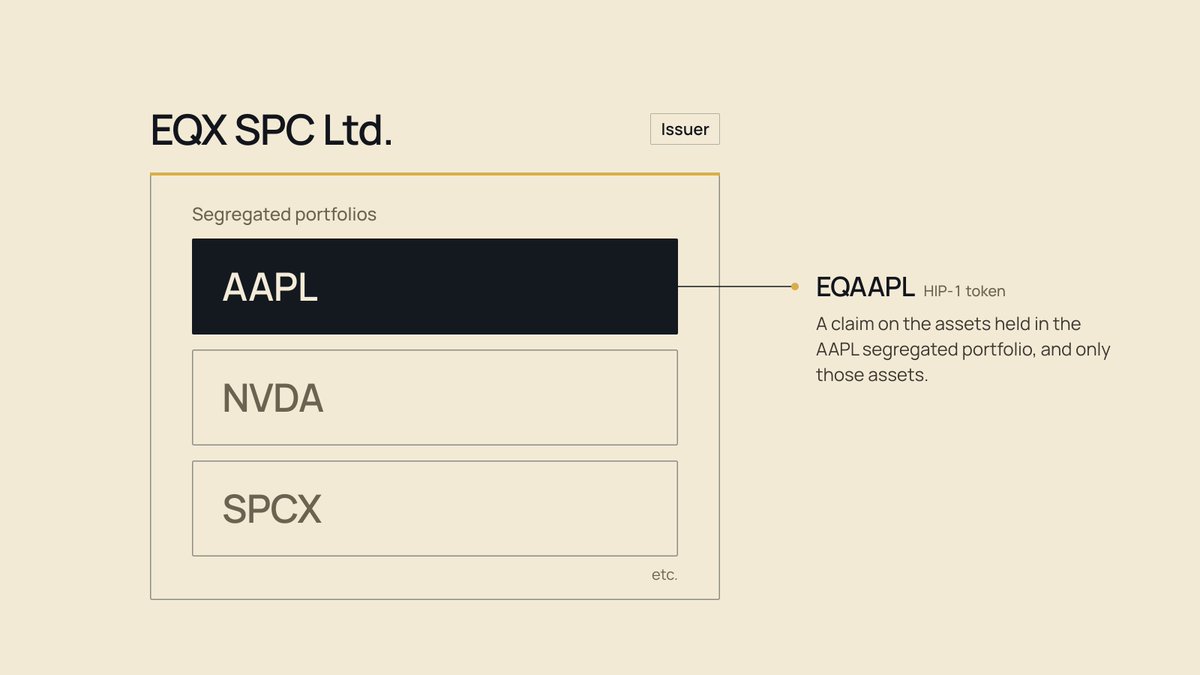
An EQX token is a share-backed, limited-recourse note issued by EQX SPC Ltd. (the issuer), a BVI segregated portfolio company. It trades on HyperCore as a HIP-1 token. Each ticker has its own segregated portfolio, and holders’ claims against the issuer are tied to that portfolio.
Authorized participants (APs) exchange shares for tokens and tokens for shares, with no issuer fee in either direction. When tokens trade above the value of their backing, APs can buy shares, create tokens and sell them. When tokens trade below it, APs can buy tokens, redeem them and sell the shares. This arbitrage helps keep token prices close to the value of the shares behind them while US markets are open.
When an AP delivers shares, they enter a custody account in EQX SPC Ltd.’s name at one of three DTC-connected custodians: @AlpacaHQ, @StoneX_Official or @ClearStreetLLC. Shares awaiting delivery are shown as in flight and are due by the next U.S. business day. From launch, our dashboard will show settled and in-flight shares separately, alongside the brokers’ own statements.
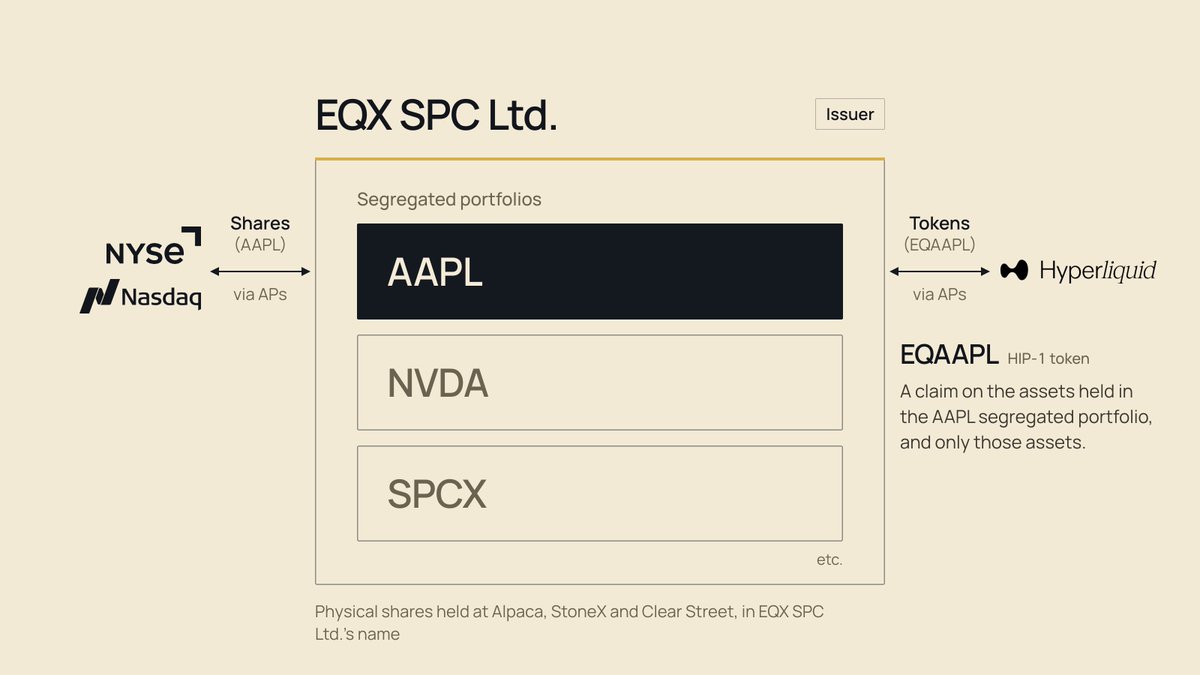
EQX SPC Ltd. issues the tokens, and each ticker’s portfolio exists only to hold its backing shares and meet its obligations to holders. The issuer is owned by the EQX STAR Trust, a Cayman purpose trust with independent governance; EQX Labs own none of it. This structure is designed to protect token holders.
EQX passes through the ownership benefits of the underlying shares to token holders:
-
Voting from day one. Holders can submit voting instructions with a wallet signature.
-
Dividends and stock splits. Dividends are reinvested into more of the same stock after applicable withholding, and stock splits are reflected in the shares backing each token. Once Hyperliquid’s proposed HIP-1 extension is live, we plan to distribute dividends directly to holders’ accounts rather than auto-reinvesting them.
We’ve designed EQX this way to give holders verifiable share backing, participation in the benefits of the underlying shares, and clear rights against the issuer. For a deeper dive, we encourage you to read our complete docs.
Why Hyperliquid’s economics matter
To make Hyperliquid the primary venue for equity price discovery, the all-in cost of arbitrage between NYSE, Nasdaq and Hyperliquid has to be extremely low, both in direct cost (fees), and indirect cost (time).
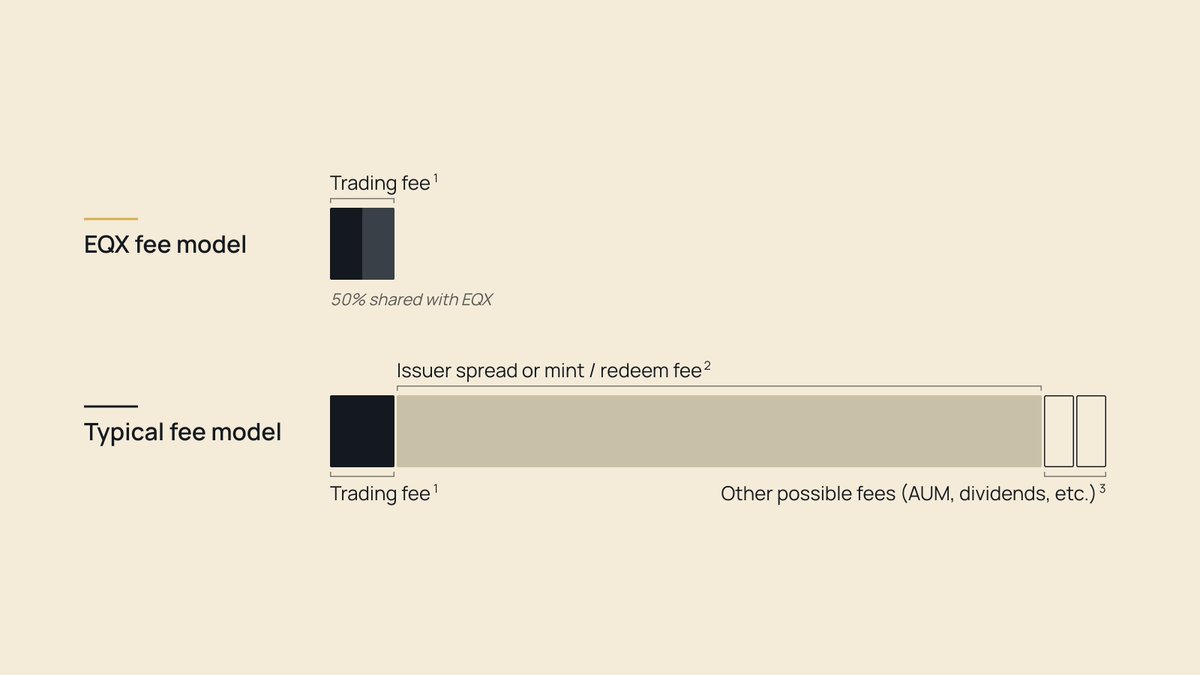
Many tokenized equity issuers today are separated from the venues where their assets trade. Because they don’t earn from secondary trading activity on DEXes of general purpose blockchains, they’re forced to fund their business through fees and spreads on create/redeem, dividends, assets under management, or elsewhere. Those fees raise the cost for token holders and constrain the market from growing.
Hyperliquid enables a different model by sharing trading fees with HIP-1 deployers.
EQX was designed around Hyperliquid’s fee model from the outset: our share of trading fees funds the business, so we charge nothing to create, redeem or hold tokens and take no cut of dividends. That makes arbitrage cheaper and gives market makers more room to quote tighter spreads. Simply bridging a token onto HyperCore, like other issuers have done, does not remove the fees or spreads built into it. It just stacks fees on top of fees.
Making Hyperliquid the home for spot equities
Our mission is to make Hyperliquid the primary venue for equity price discovery and the best place to hold and trade equities. Hyperliquid isn’t a distribution channel for a multichain tokenized equity product, it’s core infrastructure needed to give traders access to public equities with 24/7/365 uptime, security, throughput, and low fees. We believe in the long term vision to house all of finance and are building our business around its success.
We want EQX equities to become part of how traders put capital to work across Hyperliquid: held in spot, hedged against equity perps, used as collateral in lending markets, deposited into vault strategies, and more. Our first 11 markets give us a concrete starting point to grow from.
We’ve put our structure and economics in the open. Now we’re inviting the APs and distribution partners who will help put them to work to get involved. If you’re interested in becoming an AP or bringing EQX tokenized equities to your users, our DMs are open.
More to come soon.


