
Anthropic’s IPO is where the AI build switches from debt to stock
文章目录
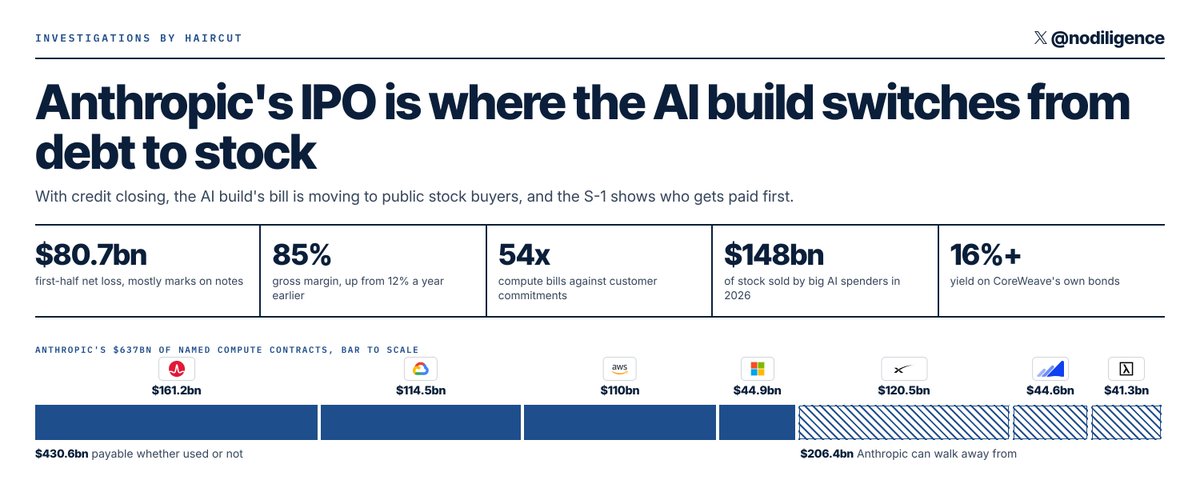
Anthropic is a much better business than I expected. It made $974m of operating profit in Q2 and has an 85% gross margin.
But most of the S-1 is about money it owes. It has $637bn of compute contracts, a bunch of loans that turn into shares, and most of its suppliers are also its lenders and shareholders. Google and SpaceX (which owns xAI) are even its competitors. This IPO is basically public investors coming in to pay for the next few years of data centres.
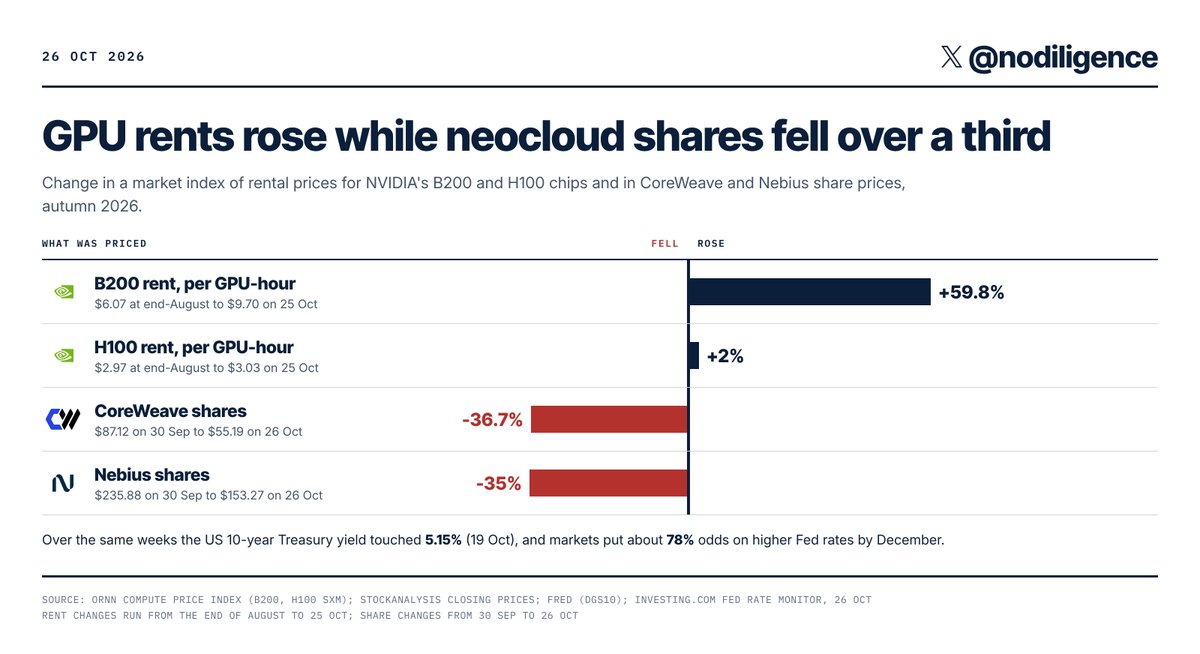
I’ve been bullish on compute for a while now and I still don’t think demand is the issue. GPU rents went up this autumn while neocloud stocks fell by a third. The funding is the issue. Lenders have mostly stopped lending unless a big investment-grade company is backing you, the big spenders are selling stock now, and Anthropic’s raise of about $100bn is the biggest one yet. I think the build keeps going and the companies getting paid in cash, mainly TSMC and Alphabet, keep making money. The ones who lose are whoever lent long-term money against short contracts, and anyone buying ANT in the first few weeks before the lockups start ending.
My thesis is pretty simple that this IPO is where the AI build switches its marginal funding from credit to public equity.
Credit for the build has mostly closed to anyone without an investment-grade name standing behind the cash flow (the day before the filing Musk said debt markets have “almost entirely shut off” for companies that depend on AI data centres), the biggest spenders have stopped buying back stock and started selling it, and Anthropic’s own contracts are built so that a growing share of its compute bill can be paid in ANT shares. The money that ends up funding this comes in through a float of about 5% to 7%, fast index entry and leveraged ETFs, while the people closest to the numbers have spent the year selling or moving up the capital structure.
The value accrues and goes to whoever is paid in cash, up front and on short terms: TSMC, and Google as the one landlord that owns the chip, the cloud and a stake in the tenant. It drains from whoever lent long against short contracts: neocloud bondholders, data-centre bonds with four-year leases under them, and Oracle. Anthropic itself is a better business than its $80.7bn loss suggests and a weaker counterparty than its suppliers’ backlogs suggest.
Rents are rising while the cost of money for the build jumps
The Fed raised rates to 3.75% to 4% on 16 September, its first hike since 2023, and its chair Kevin Warsh has flagged AI spending as more than half of the 9% rise in business investment. Headline inflation was 3.7% in September with energy up 20.4%, Brent was about $115 for December delivery, the 10-year Treasury touched 5.15% on 19 October, and futures put about 78% odds on higher rates by December. For this IPO that chain matters more than any model launch. The AI build is now big enough to be part of the inflation the Fed is fighting, so it raises its own cost of capital: more capex pushes rates up, and higher rates cut the price of the long fixed-rate paper that funds the next round of capex.
Meta’s Hyperion data-centre bond shows that loop at work. It pays 6.581% to 2049 and fell to a record low of 94.4 cents while Meta’s own stock was rising, and later slipped to just under 92 cents. Part of that is the 10-year at 5%. The other part is in Meta’s 10-Q: each of its joint-venture leases has an initial four-year term, and Meta’s residual value guarantees across its two data-centre joint ventures, up to $41.49bn, carry no recorded liability. A bondholder to 2049 is really underwriting whether Meta renews in year four.
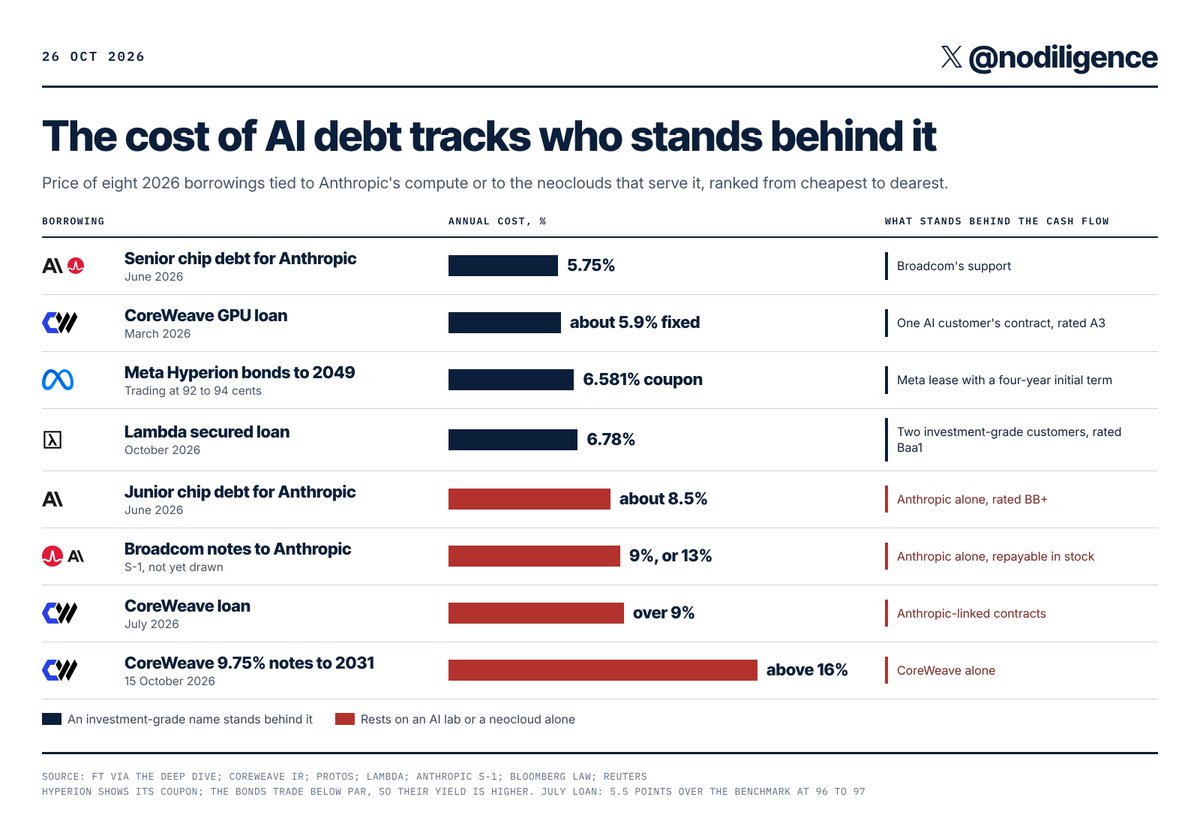
CoreWeave’s own borrowing is the cleanest record of the shift. In March it raised $8.5bn at 2.25 points over SOFR with an A3 rating, backed by one AI customer’s contract. By late July a $2.6bn loan tied to its Anthropic and Jane Street deals was being sold at 5.5 points over the benchmark, at 96 to 97 cents. The 9.75% notes it priced at 102 in April yielded above 16% on 15 October. Meanwhile its new contracts are priced at about $40m per megawatt on three-to-six-month terms. That is the trap for every neocloud: the most profitable contracts it can sign today are the least financeable, because lenders size GPU loans on long take-or-pay contracts with investment-grade customers.
Sources: The Deep Dive; Lambda; Protos; CoreWeave; SEC filing; Bloomberg Law; Yahoo Finance
In every one of these deals the price tracks who stands behind the cash flow rather than the GPU itself. Anthropic’s credit costs 5.75% with Broadcom’s name on it and about 8.5% on its own, and KBRA gave it that BB+ without free cash flow or EBITDA figures from the company. Anthropic-linked contracts cost CoreWeave more than 9% in a secured loan, and CoreWeave’s own unsecured bonds yielded above 16%. Every structure that reached investment grade did it by borrowing someone else’s balance sheet, and the slice carrying the AI tenant’s own risk is always the small one. Broadcom’s 9% notes, where interest is added to the loan instead of paid, are what a vendor accepts when outside junior money would cost more or would wait for the IPO.
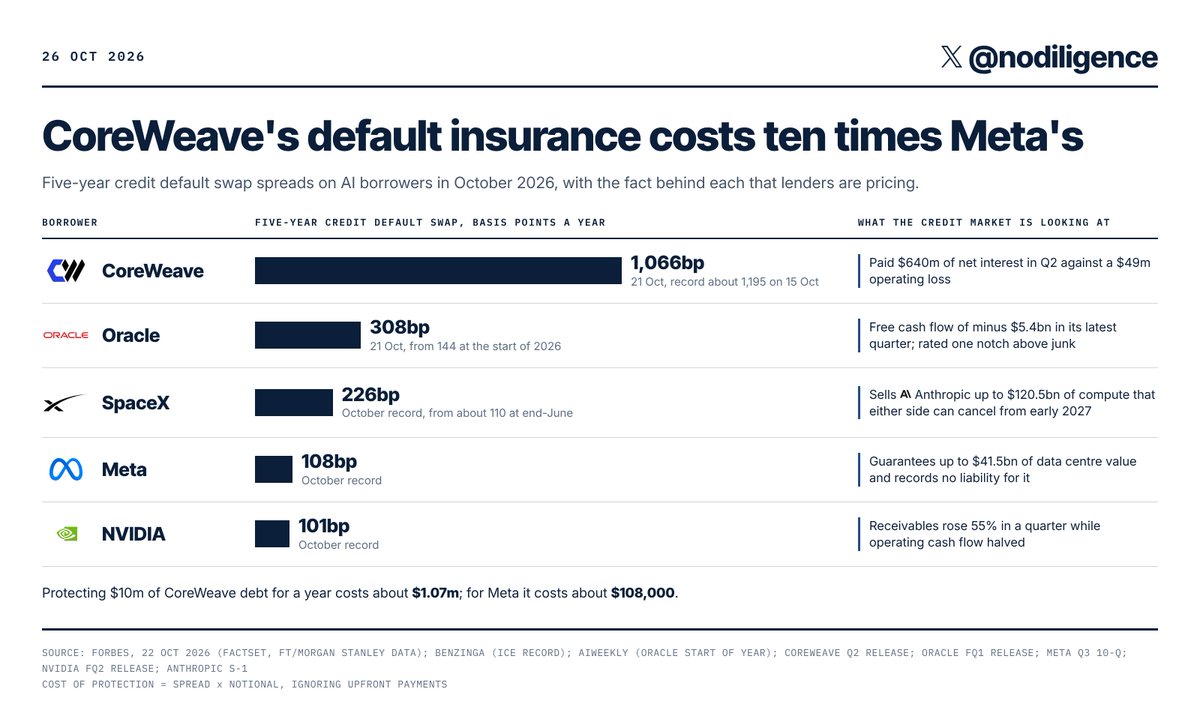
The credit market sorts the industry by distance from a hyperscaler balance sheet. CoreWeave sits near 1,066bp, Oracle near 308bp after starting the year at 144bp, SpaceX at a record 226bp, Meta at 108bp and NVIDIA at 101bp, per Forbes’ tally of FactSet and Morgan Stanley data. The equity market priced none of that on filing day, when NVIDIA, Broadcom, AMD and Micron rose 2% to 3%. Credit desks are hedging the layer that owes the money while equity desks own the layer that is owed, and I think the credit desks have it right about who ends up holding the loss
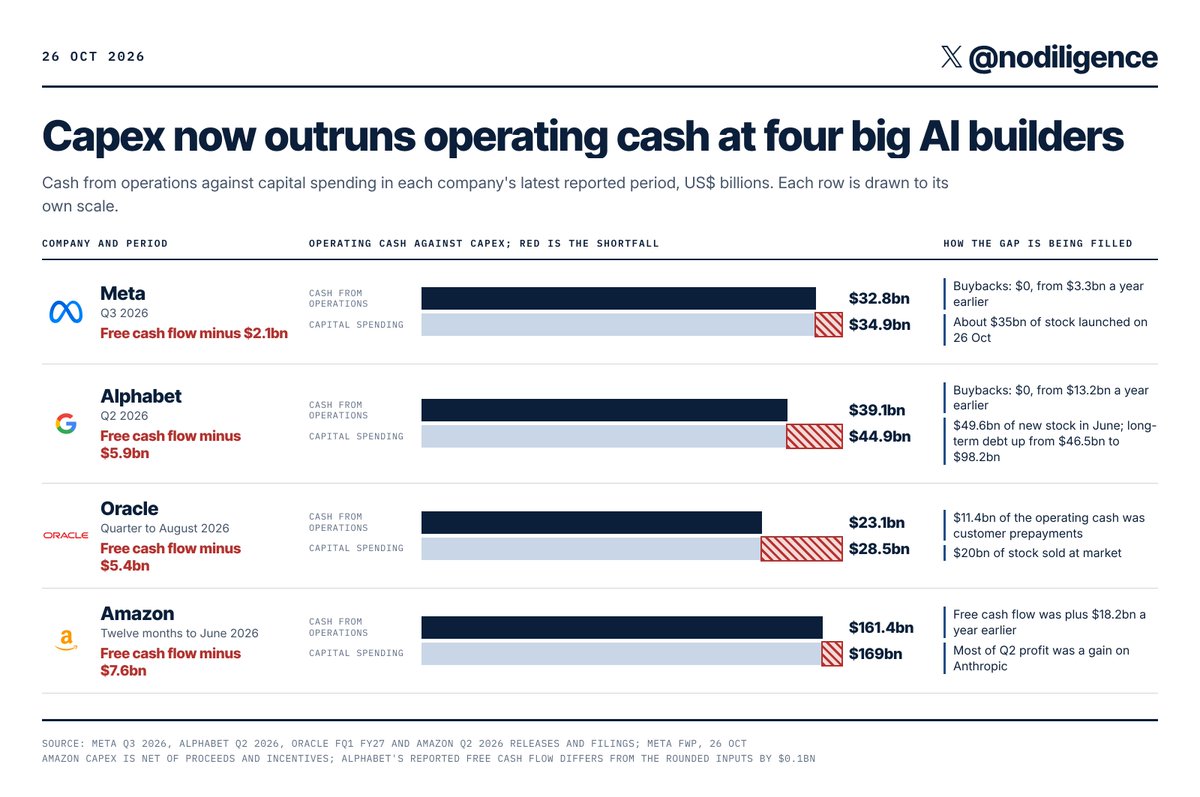
The biggest spenders stopped buying back stock and started selling it
Sources: Meta; SEC filing; Alphabet; Nasdaq release; Oracle
Four of the largest builders now run negative free cash flow, and the two that stopped buybacks did it in the same year their CEOs said demand outruns supply. Zuckerberg said in July there is “nowhere near enough compute” and that outsiders offer Meta’s capacity “a significant premium over what we paid for it”. If that premium were large and long-dated, Meta could rent out capacity and keep its cash. It sold stock instead, and NVIDIA, AMD and Broadcom indicated non-binding interest in buying up to $5bn of it. Vendor financing has moved from the neoclouds up to a hyperscaler, and suppliers offering to buy their customer’s stock so the customer can keep buying their chips is the clearest sign in this cycle that end demand is not yet paying for the capex at the pace it is growing.
Oracle is the version of this with the least room. S&P cut it to BBB- on 9 July and expects a free operating cash flow deficit of nearly $42bn in fiscal 2027, with OpenAI about half of its $638bn backlog at the time. Its operating cash flow now includes $11.4bn of prepayments from customers, so part of what Oracle reports as operating cash is customers financing Oracle’s build.
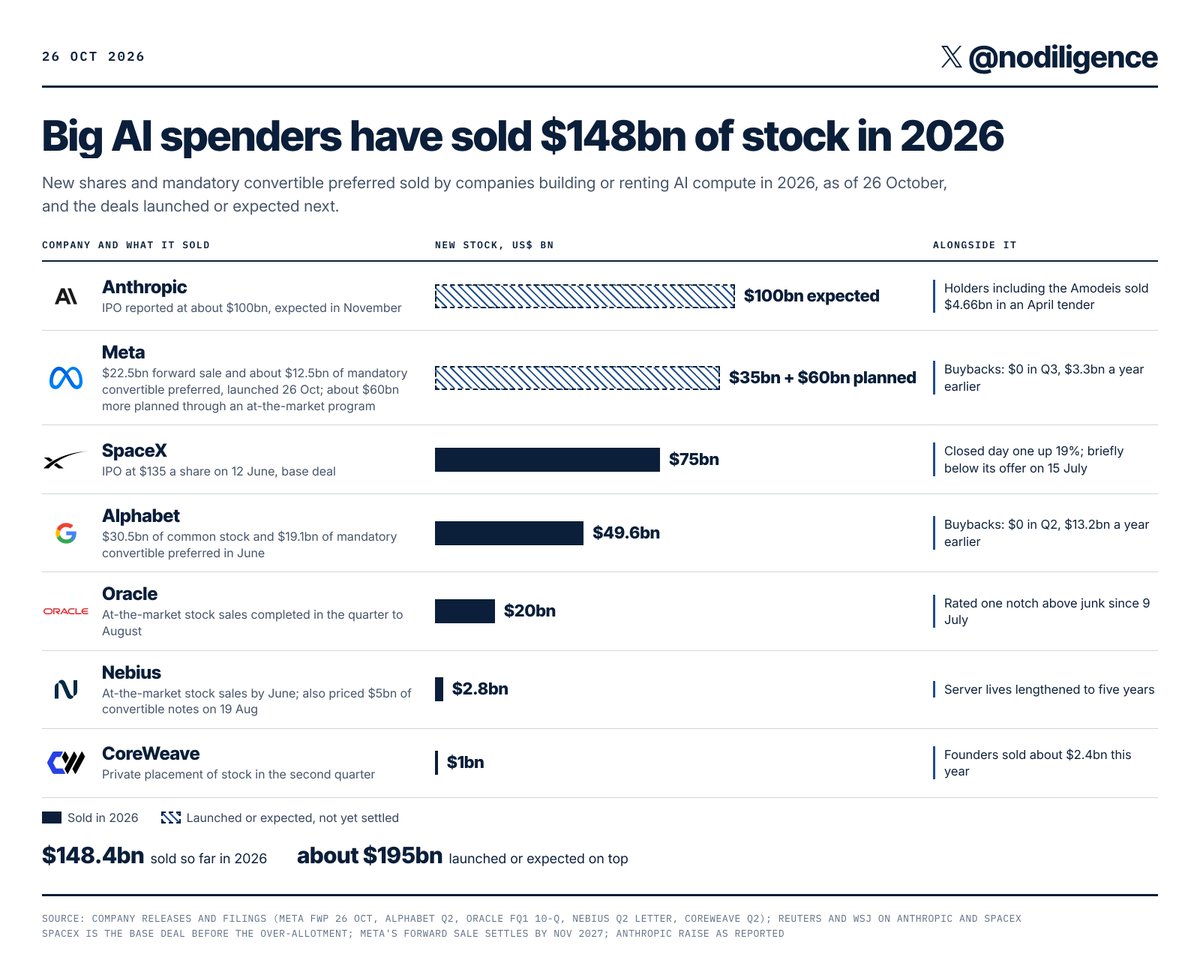
Add Anthropic’s reported $100bn, the $35bn Meta launched on 26 October and its planned $60bn, and AI companies are asking the stock market for about $340bn inside a year, with the Fed hiking. The bond market had already signalled the limit: Amazon, Alphabet, Meta and Oracle sold about $194bn of bonds by 7 July against $108bn in all of 2025, the extra yield needed to clear new deals rose from 2.25bp to 12bp, and order books fell from nearly five times covered to under two. The Bank of England’s financial policy committee cites Morgan Stanley’s estimate of about $450bn of AI-related debt by early September and JPMorgan’s estimate that about $4.1tn of AI capex will be debt-financed between 2026 and 2030. Equity is the window still open, which is why this many issuers are going through it at once.
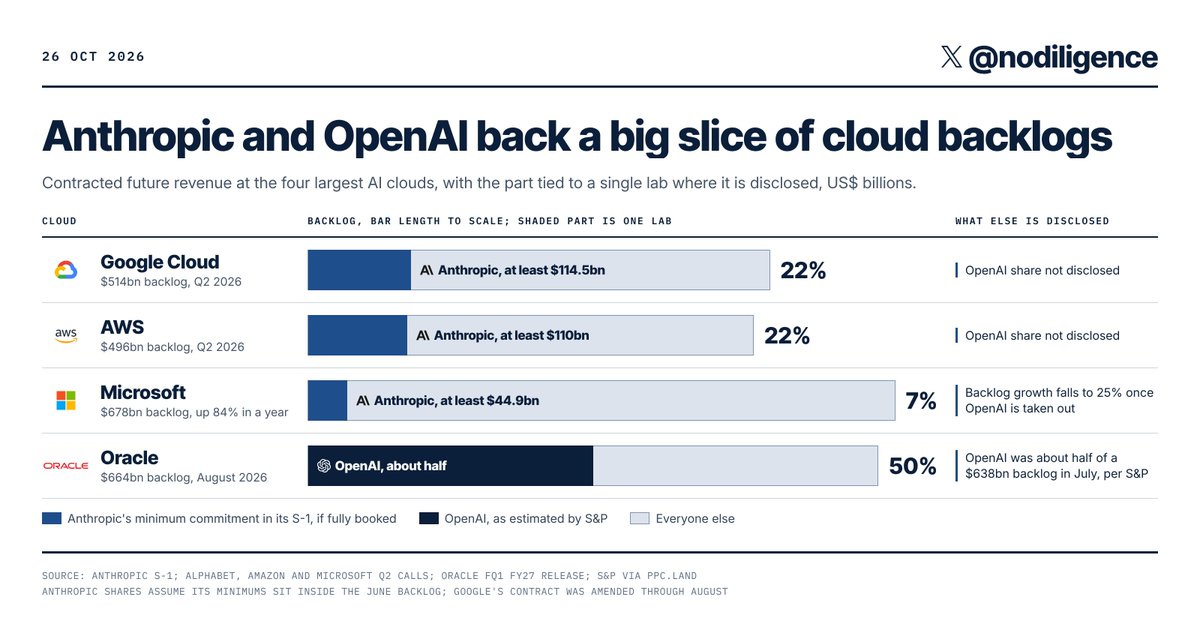
A large share of cloud backlog and profit rests on two private labs
Sources: Investing.com; Investing.com; StockAnalysis; PPC Land
The growth story at the clouds and Anthropic’s liabilities are the same contracts seen from two sides. If the minimums are fully booked, a fifth of Google Cloud’s and AWS’s backlog is one customer that bills its own customers by the token, and most of Microsoft’s backlog growth is one other customer. That is why I treat the IPO as a refinancing of hyperscaler backlog with public equity: the money raised from ANT buyers is what lets Anthropic keep adding to a fifth of two clouds’ booked revenue.
The profit side is more concentrated still.
-
Alphabet booked a $99bn gain on equity securities, worth $6.26 of its $9.11 of earnings per share, which Fortune attributes mostly to its Anthropic and SpaceX stakes since Alphabet does not split it out, and Microsoft added a $3.2bn gain on Anthropic.
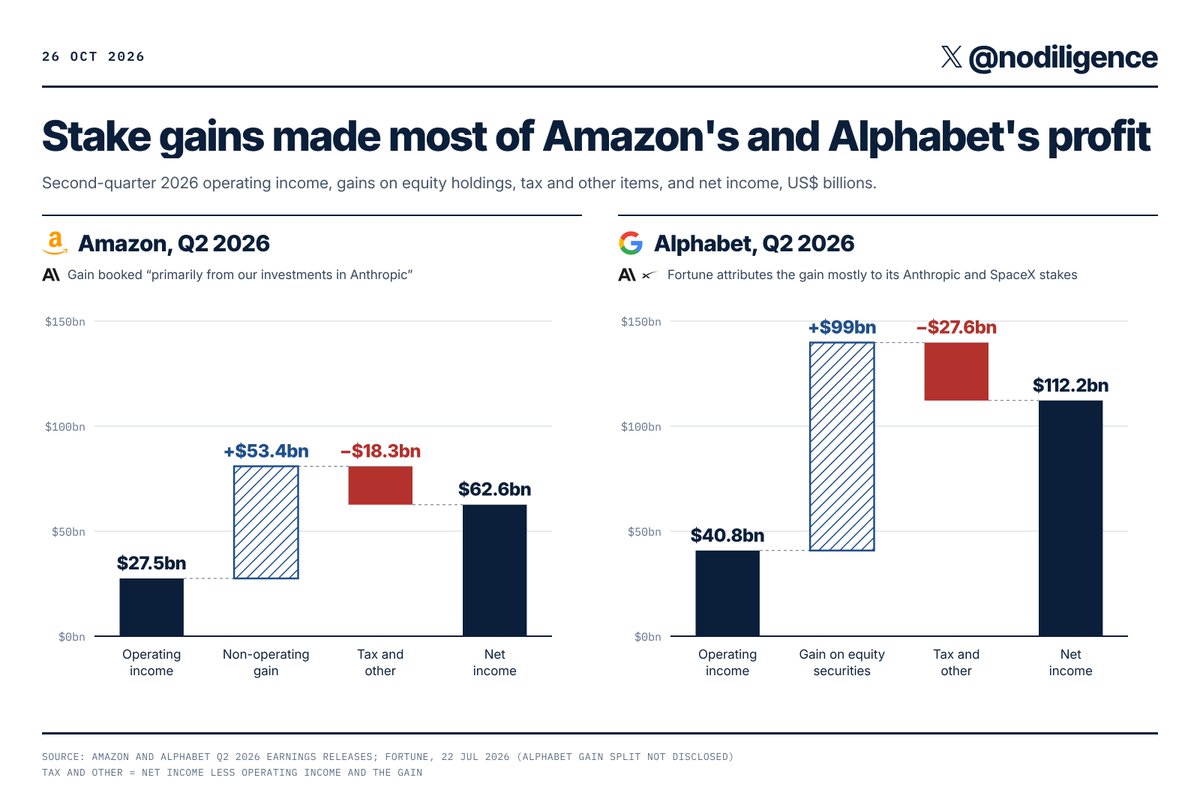
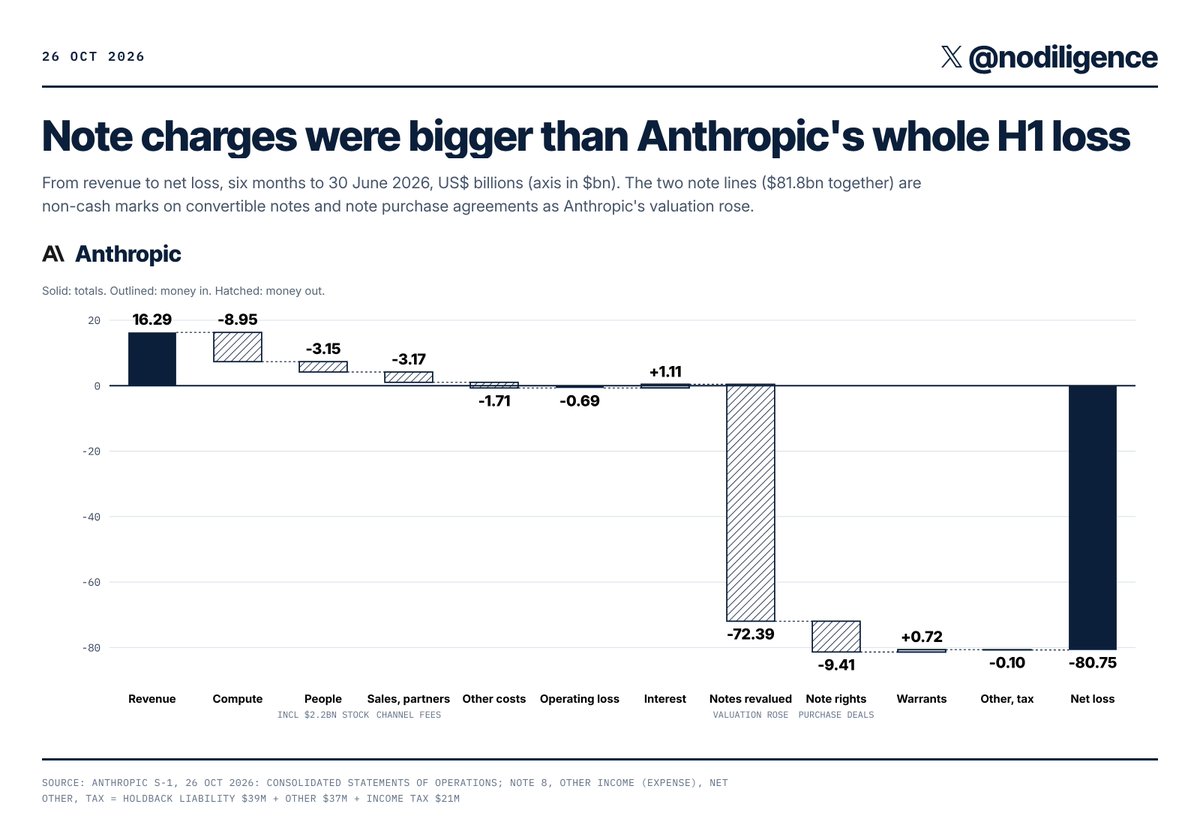
Anthropic’s $72.4bn first-half charge for the change in fair value of its convertible notes is the same revaluation counted from the other side. Once ANT trades, its price flows into Amazon’s and Alphabet’s non-operating income every quarter, so a weak ANT becomes an earnings miss at two of the largest index weights. Both have a direct interest in a strong book, and Google holds an option to buy up to $10bn of stock at the IPO price. The IPO turns a private mark into a public input to S&P 500 earnings.
Anthropic’s own numbers are better than the loss and harder than the story
Revenue was $4.59bn in 2025 and $16.29bn in the first half of 2026, with Q2 alone at $11.56bn. The filing leaves Q3 blank, but the business section puts Q3 revenue at 86 times Q4 2024’s and the risk factors put Q4 2024 at $197m, about $16.9bn, close to the $16.8bn reported by the FT. Anthropic leads enterprise LLM spending with 40% against OpenAI’s 27% in Menlo’s latest survey, and Ramp’s September index has it ahead on business adoption, 43.8% to 40.6%.
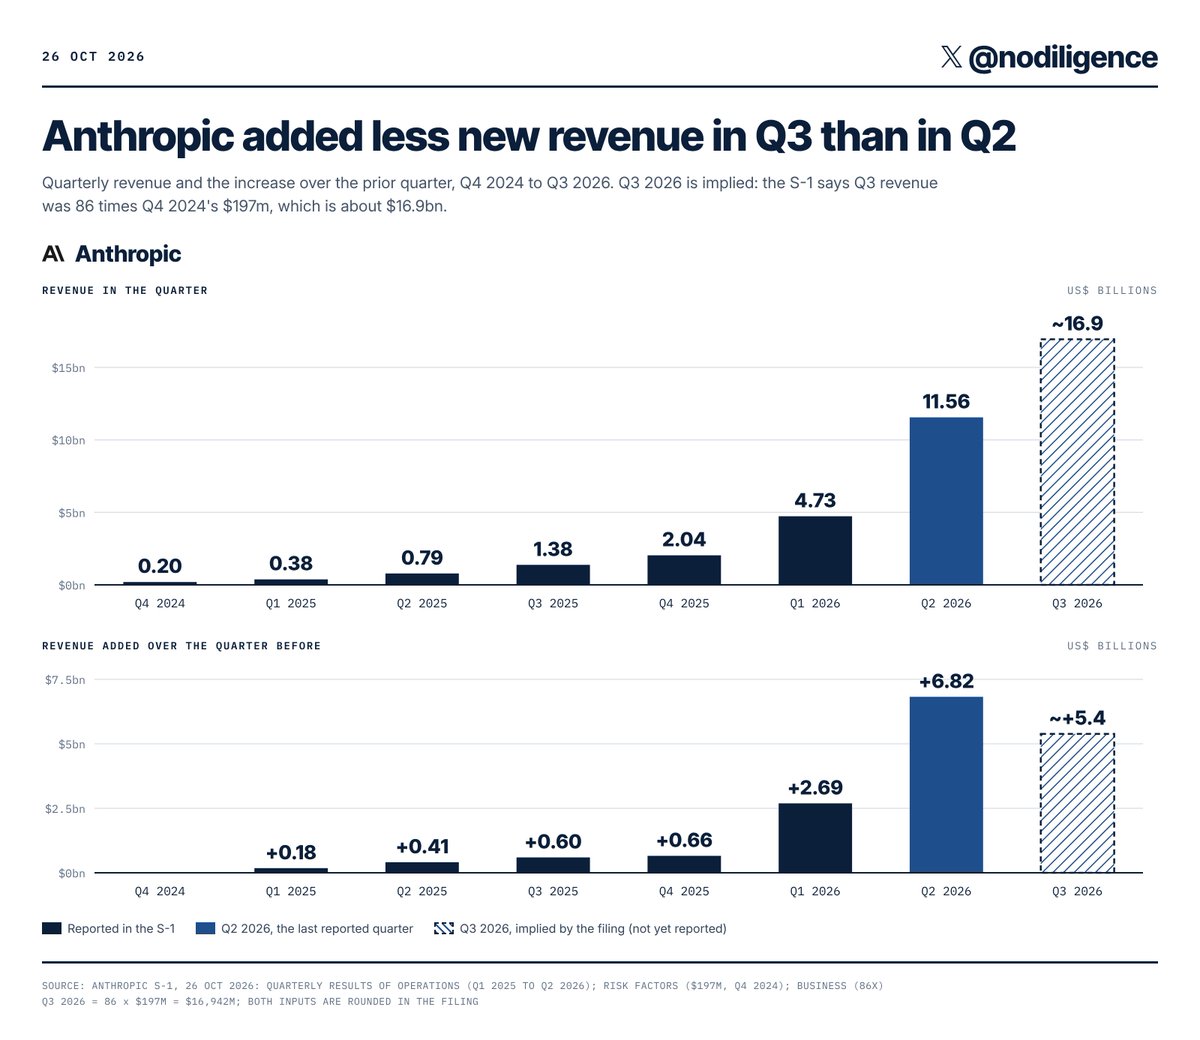
Q3 is still about 46% growth on Q2. What changed is the size of the step: Q2 added $6.82bn of quarterly revenue and Q3 about $5.4bn, the first quarter in the series to add fewer dollars than the one before. Model versions released in the six months to 30 September produced over 80% of Q3 revenue, and the September releases cut cost per task by about 25% for Fable 5.1 and about 40% for Opus 5.5. A 40% cut means usage has to grow about two-thirds just to keep revenue from the same work flat. Revenue arrives in jumps tied to releases and price cuts, and the jumps got smaller just as the long-dated bills start landing
The margin is the strong part. Note 8 restates costs by function and puts cost of revenue at $2.38bn against $16.29bn of first-half revenue, an 85% gross margin, up from 12% a year earlier.
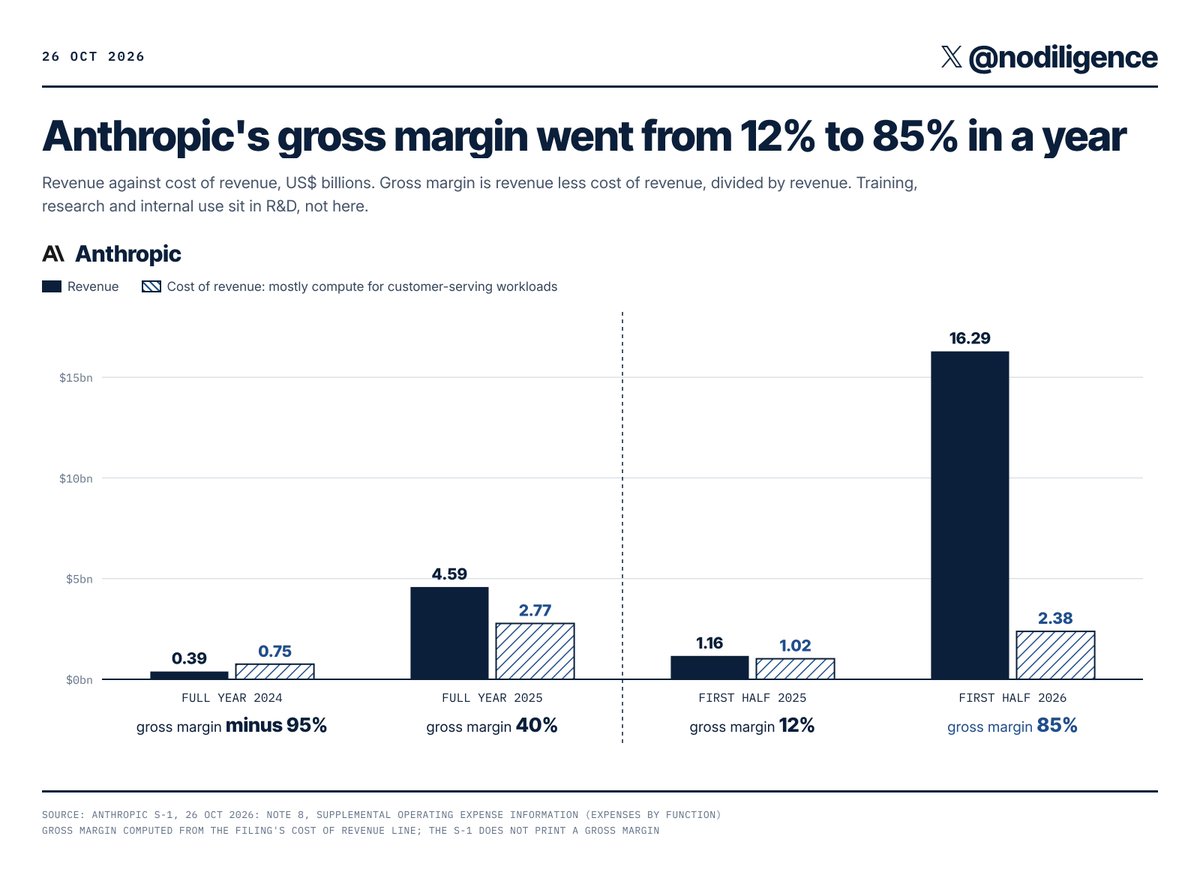
That 85% rests on Anthropic’s own split of one compute pool between serving and training, and I suspect part of it reflects supply that never arrived: the filing says Anthropic has in the past sought more compute from its clouds than they were willing to provide and expects more short-term compute at higher prices to compress its operating margin in the near term. The rental prices in the first chart are a good proxy for that short-term compute. Rising GPU rents help the neoclouds’ collateral and hurt Anthropic’s margin at the same time
The loss is mostly paper: the operating loss was $693m for the half, with a $974m operating profit in Q2, and operating cash flow was $3.93bn against $482m of capex. The $80.7bn net loss comes from marks on notes held by the same companies that rent Anthropic its compute.
On valuation, a listing at $1.5tn to $2tn is about 22 to 30 times Q3’s revenue annualised. OpenAI is negotiating to raise $30bn or more at $1.4tn before the new money, about 52 times its latest reported quarter of $6.7bn annualised. Anthropic books its cloud marketplace sales, 48% of first-half revenue, gross and puts the clouds’ cut in its expenses, which flatters its side a little, but the gap is still wide. Public buyers are being offered the lab that made an operating profit in Q2 at a lower multiple than private investors are paying for the one that did not, which tells you the public discount for the financing risk in this piece is already large.
Anthropic signed hard contracts with the strong and soft ones with the weak
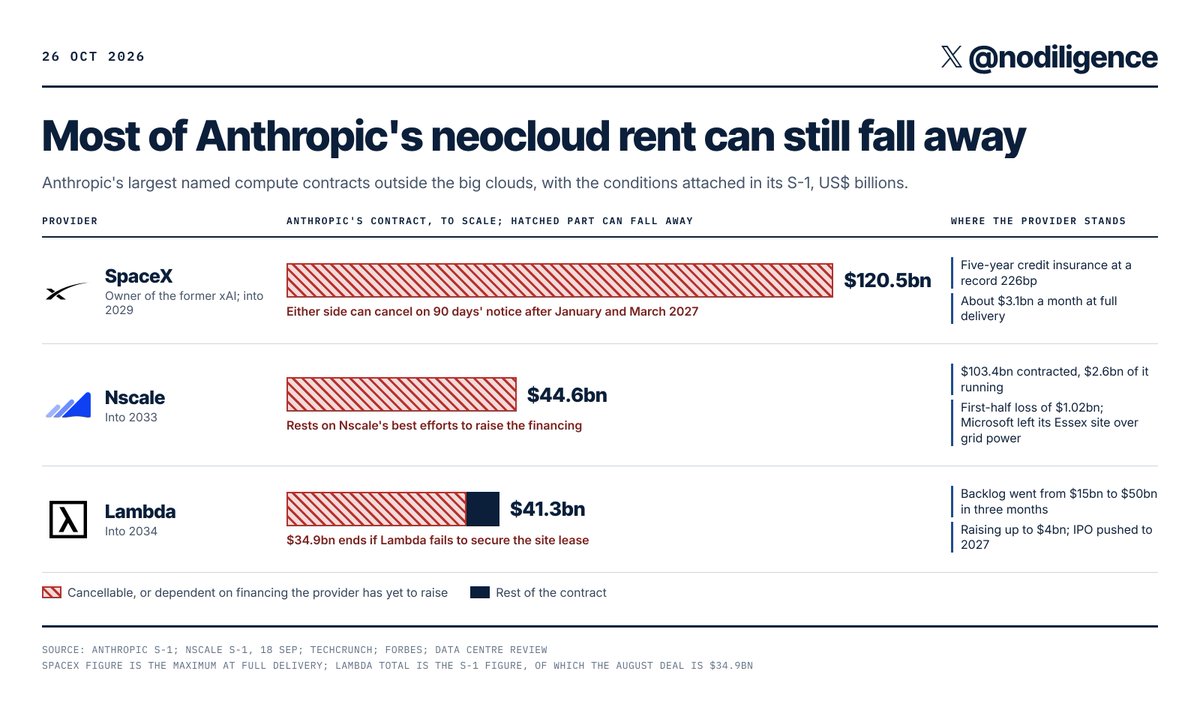
The filing puts dollar figures on seven compute contracts worth about $637bn. The four with Google, Amazon, Microsoft and Broadcom, $430.6bn in all, are payable whether the capacity is used or not, or are leases that cannot be cancelled short of a default. The three with SpaceX, Nscale and Lambda are maximums Anthropic can walk away from or pays only on delivery.
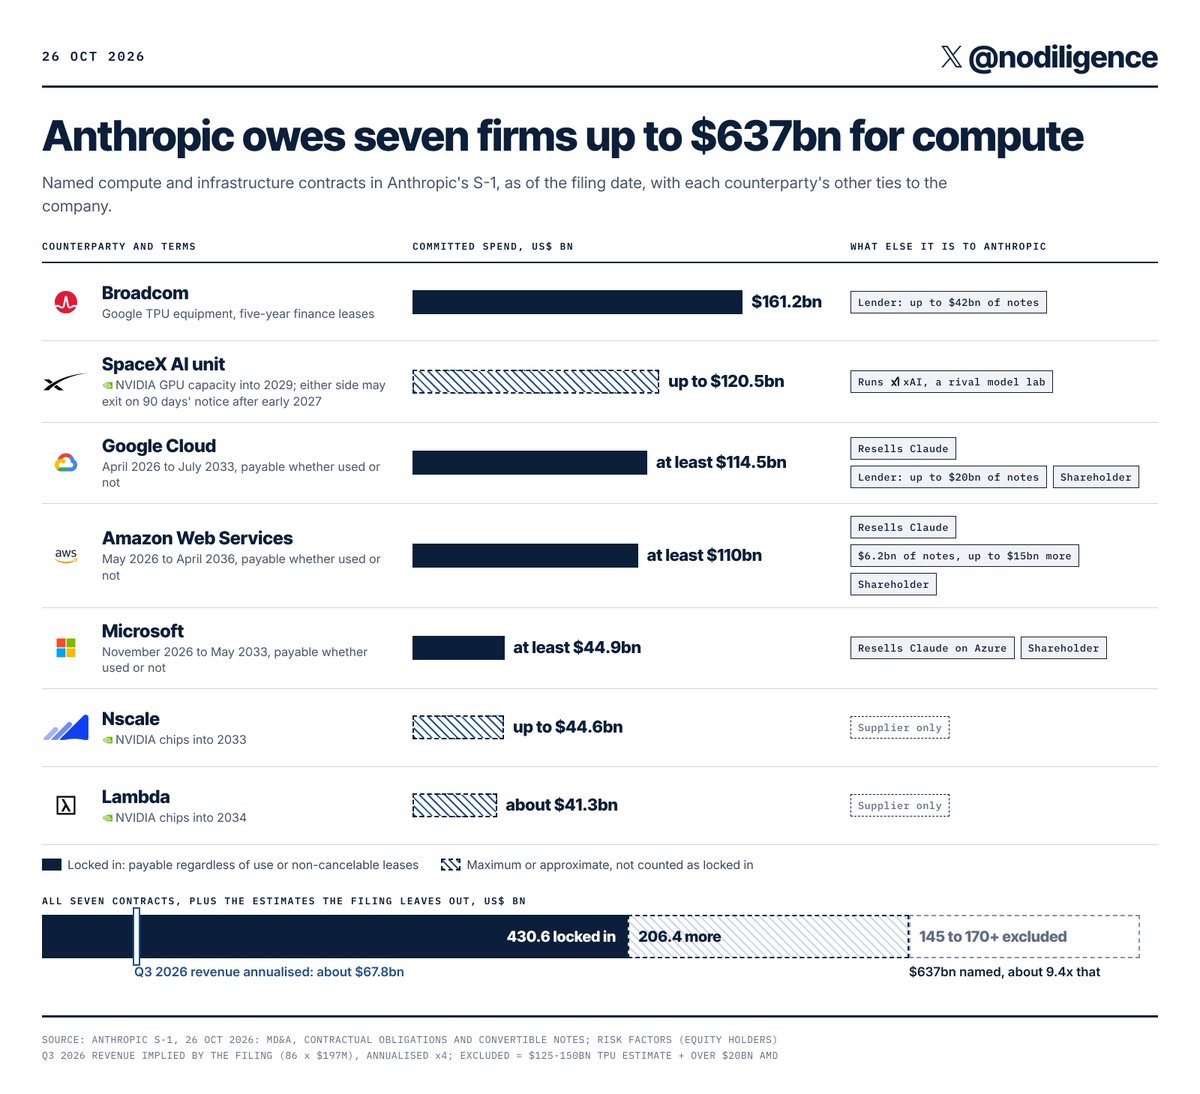
That design is smart for Anthropic, and it moves risk to the providers least able to carry it. The flexible layer is where the neoclouds sit.
Sources: SEC filing; Forbes; SEC filing; Data Centre Review; TechCrunch; TeraWulf; Nasdaq release
Two smaller arrangements sit outside the chart. TeraWulf signed a 20-year lease worth about $19bn for about 401MW, with investment-grade credit support for Anthropic still to be named, while Google already stands behind $600m of a separate TeraWulf lease to Fluidstack, which also serves Anthropic. CoreWeave has Anthropic as a customer below the S-1’s named contracts, and it carried $640m of Q2 net interest against a $49m operating loss on new contracts that run three to six months.
Each of these companies built its backlog on Anthropic, and Anthropic kept the option to leave. Nscale has 2.5% of its contracted value running. Lambda tripled its backlog in a quarter mostly on one deal it can lose if a lease falls through. SpaceX is the biggest neocloud on the list and its owner is the loudest bear on the rest of them: Musk said 200+ neoclouds face “guppy-level death and consolidation” the day before the filing, while holding a $120.5bn contract that turns into a 90-day rolling deal from early 2027. Gartner expects more than 80% of neoclouds to stop operating independently by 2030. If Anthropic’s growth slows, its first move is to stop renewing the flexible layer, and the neocloud lenders and shareholders take that loss before any hyperscaler does.
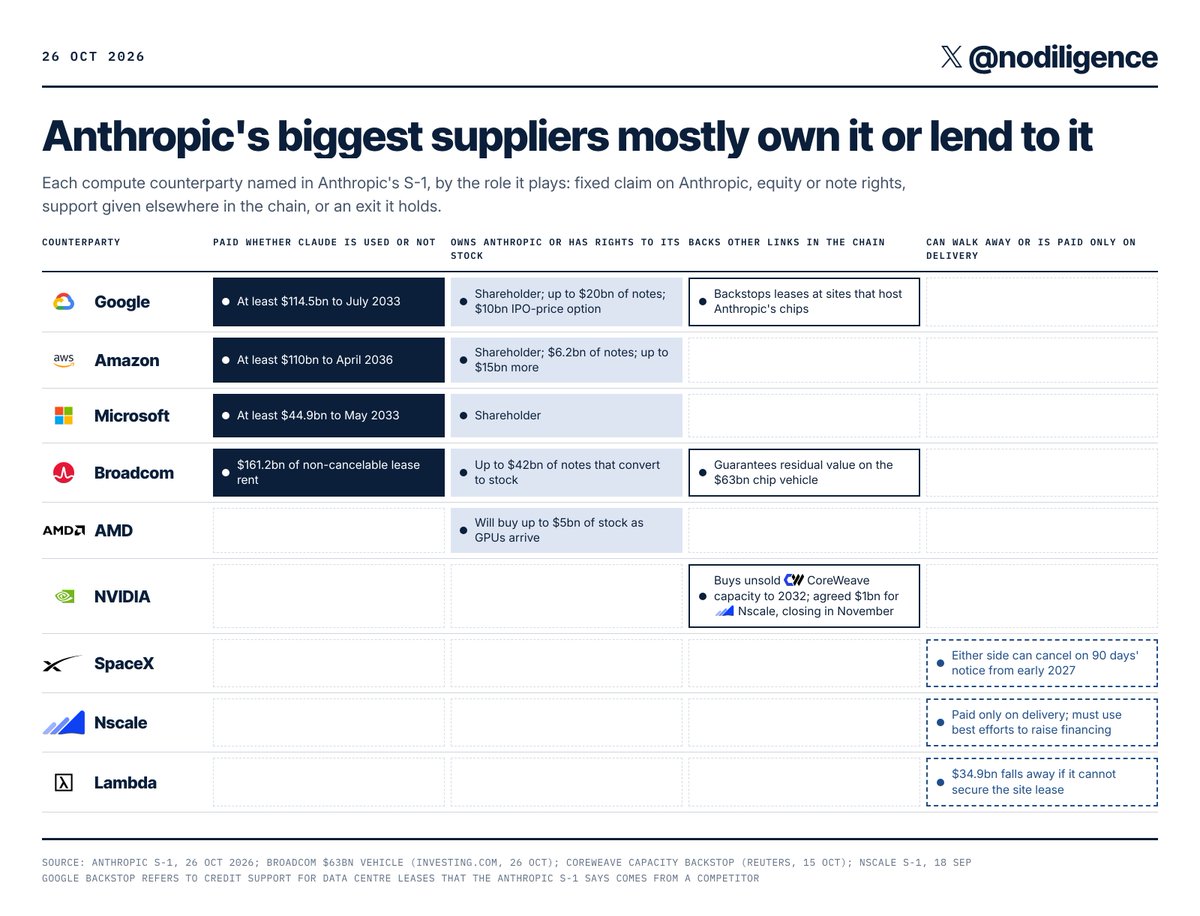
Google is Anthropic’s largest take-or-pay cloud claim, behind only Broadcom’s lease rent, a shareholder with a 14.99% cap, a note lender whose draws are tied to conditions in Anthropic’s third-party compute agreements and revenue targets, and the credit behind some of the data centres that host Anthropic’s chips. The S-1 says some of Anthropic’s capacity depends on “credit support provided by a third party that is also a competitor”. Alphabet’s backstops for data-centre payments reportedly rose to $43.8bn of notional exposure by June from $16.9bn at the end of 2025, and it took about 5.4% of Cipher for backing one Fluidstack lease in 2025. Google is the lender of last resort for its main model rival’s compute, and it collects rent, notes, equity in the landlords and marks on its Anthropic stake on the way.
The bills run for a decade, and part of them can be paid in ANT stock
At 30 June the notes showed $265.6bn of fixed or minimum purchase commitments and $321.4bn of leases signed but not yet started, and Anthropic signed about $245bn more between July and the filing. Its customers had committed to $10.8bn.
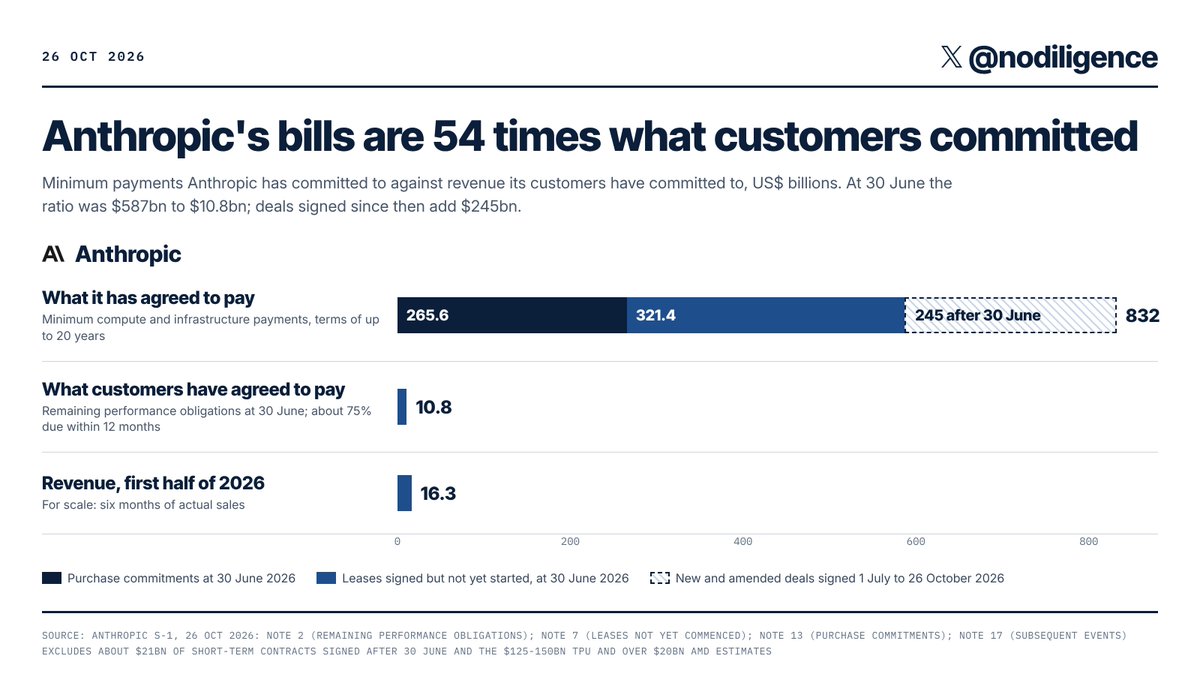
The S-1 also says Anthropic has “significantly underestimated our compute requirements” in the past, which is the stated reason for buying this much. Amodei put the risk of the opposite mistake plainly earlier this year: off by a year on growth and you go bankrupt. The named compute contracts end between 2033 and 2036, but the filing puts the tail of its commitments out to 2045, and some power deals run 20 years with take-or-pay terms and uncapped fuel pass-throughs, while many top customers can cut or stop spending at any time. With US energy prices up 20.4% in a year, that fuel clause is the macro risk sitting inside the filing.
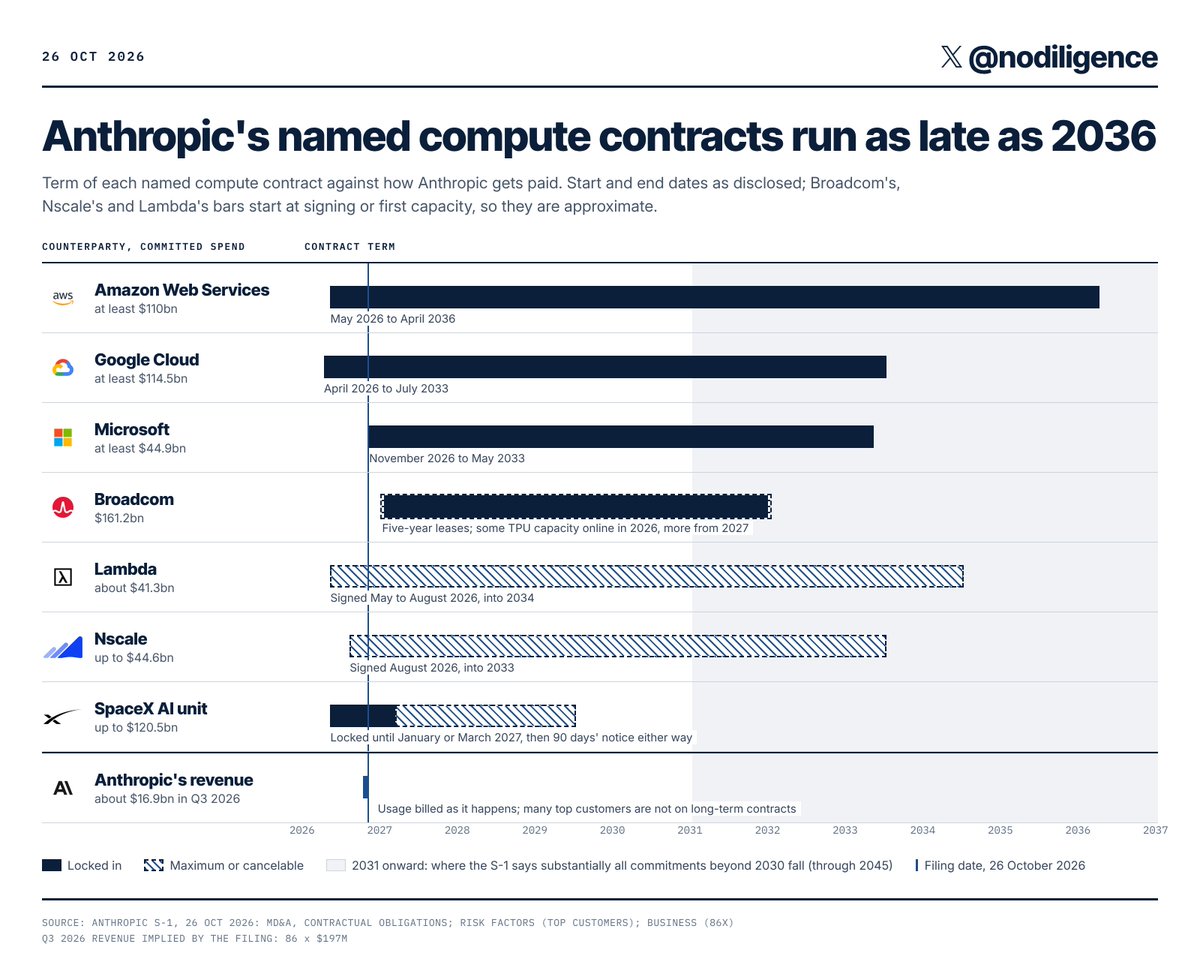
The part of the filing I think the market has missed is how much of this bill can be settled in shares. Broadcom can lend up to $42bn only to pay Broadcom’s rent; the notes convert into stock at 90% of the 30-day average price, or 85% if revenue conditions are missed, and come with a shelf for resale and up to three underwritten offerings a year. Draws on Amazon’s $15bn facility are settled in shares at the 30-day average as compute milestones are hit. Google’s $20bn can be settled in shares at the 30-day average, with resale registered within 60 days of each quarterly closing. AMD buys up to $5bn of stock as its GPUs are delivered.
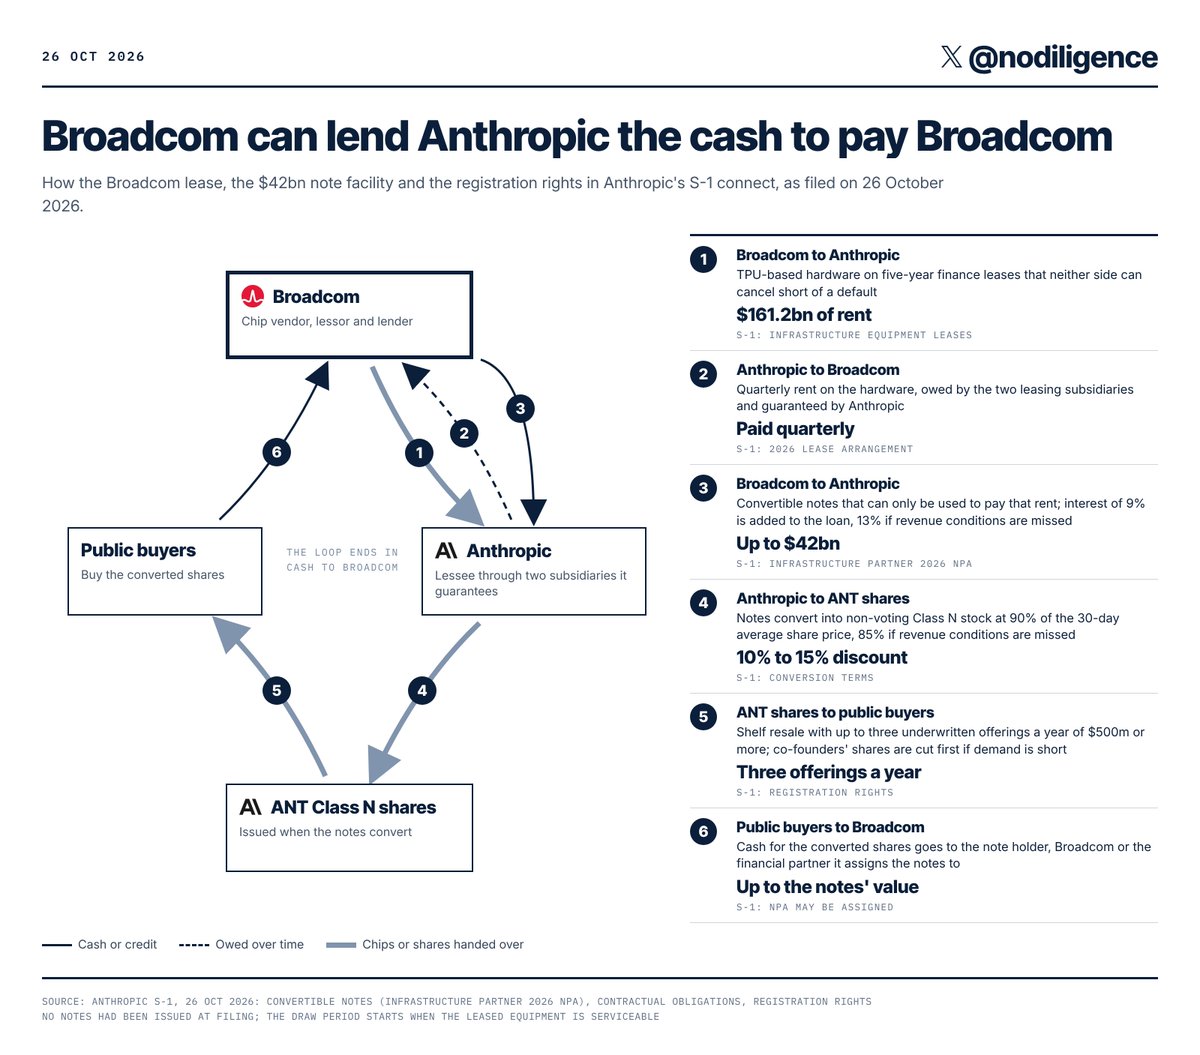
Put together, the compute bill and the share count are linked: the more compute Anthropic draws from these suppliers, the more new shares it can issue to them, and the suppliers hold registration rights to sell. Broadcom can also assign its notes to a “designated financial partner”. A financial holder of notes that convert at a 10% discount to a trailing average price would normally hedge by selling ANT short, which makes it a steady seller. Broadcom already sits on three sides of the same risk, as lessor, lender and, since 26 October, guarantor of residual value to the banks on a $63bn vehicle that buys its chips and leases them to Anthropic. Its AI revenue grew 221% last quarter while receivables almost doubled from $7.1bn to $13.7bn in nine months. The June chip platform it endorses already finances part of that revenue, and the note facility and the $63bn vehicle will finance more.
Public buyers get the economics, little say and a supply calendar
Just before the IPO a single Class F share goes to an LLC owned by the seven co-founders and carries 50.1% of the vote on everything put to shareholders. The Long-Term Benefit Trust elects four of seven directors, and the strategic holders sit in non-voting Class N, so the companies owed the most money have no vote.
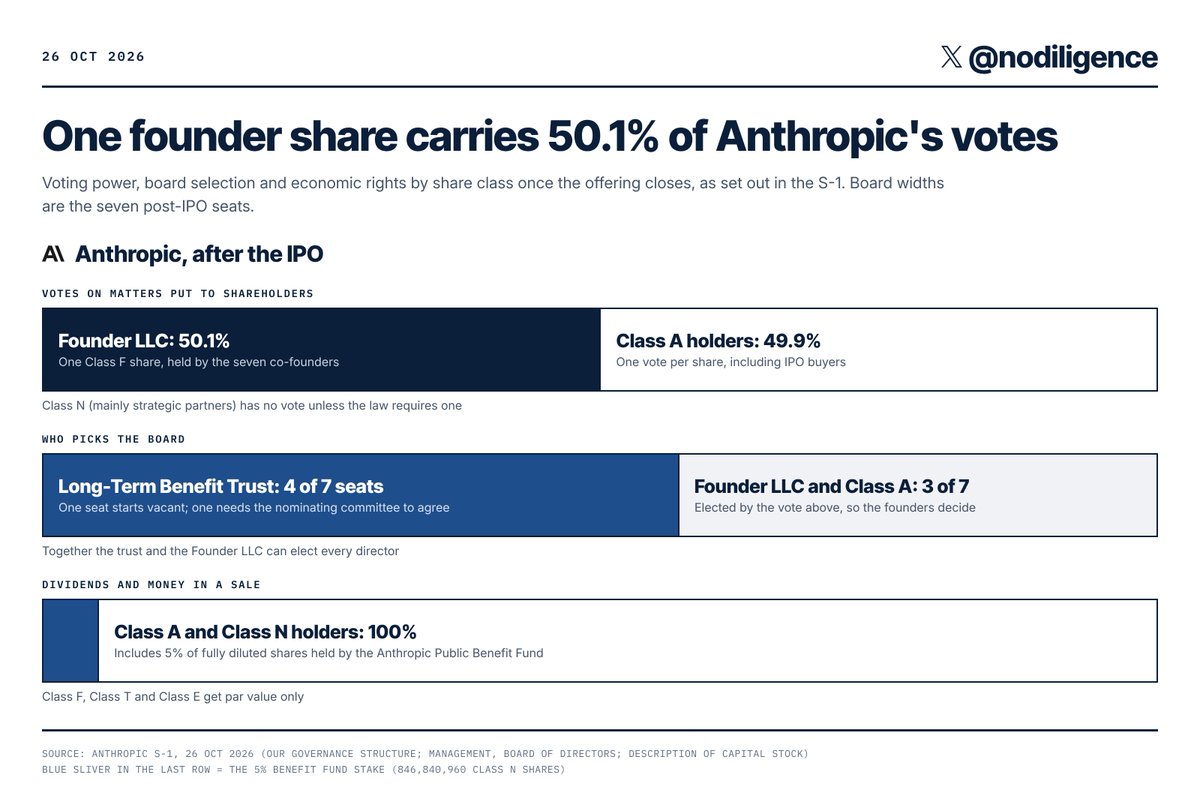
Anthropic has also put 846,840,960 Class N shares, 5% of fully diluted shares, into its own Public Benefit Fund, and the board can issue the fund another 2% each time the stock rises 50% above the last milestone, starting from the IPO price.
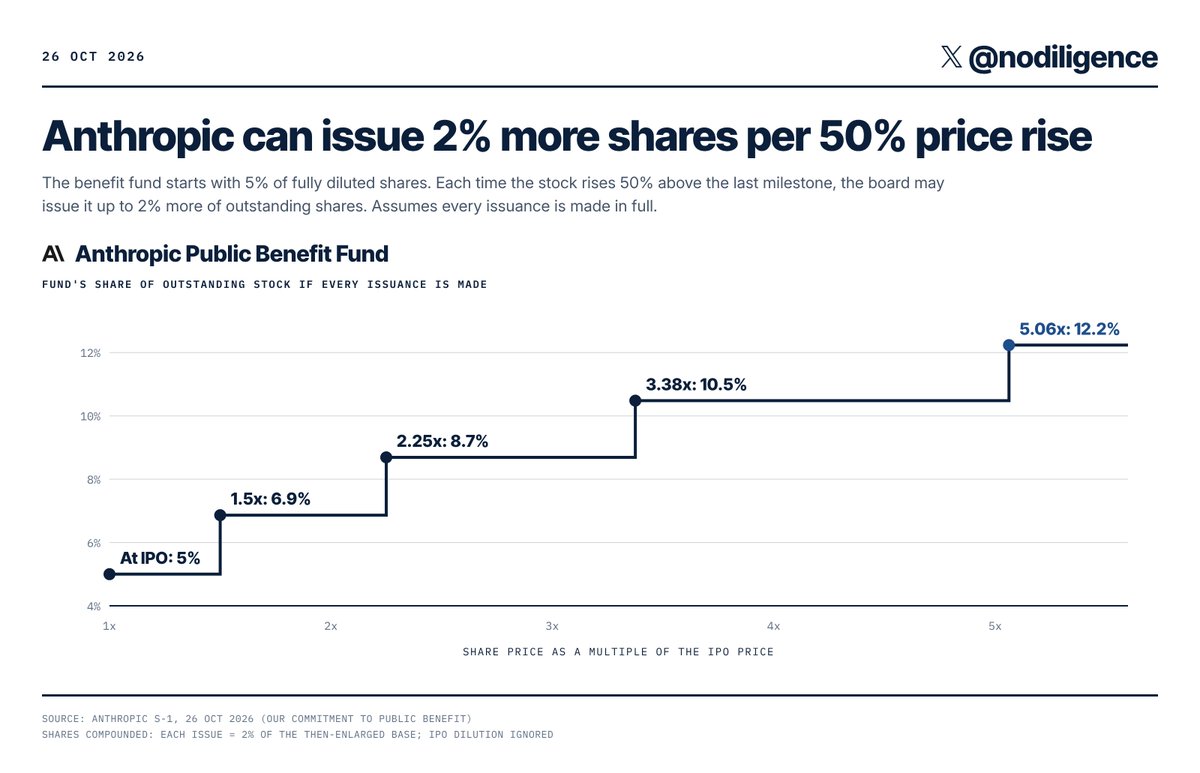
A buyer gives up a slice of the upside in exactly the scenarios where the stock does well, on top of the supplier conversions above. Against all that dilution, the deal itself is built for a strong start. Goldman Sachs and Morgan Stanley lead 22 banks on a raise of about $100bn at $1.5tn to $2tn, a float of roughly 5% to 7%. Under rules adopted this year, the Nasdaq-100 adds a top-40 IPO after its 15th trading day, with no minimum float and an index weight of up to three times the float, so a small float earns triple weight. GraniteShares has filed 2x long and 2x short Anthropic ETFs.
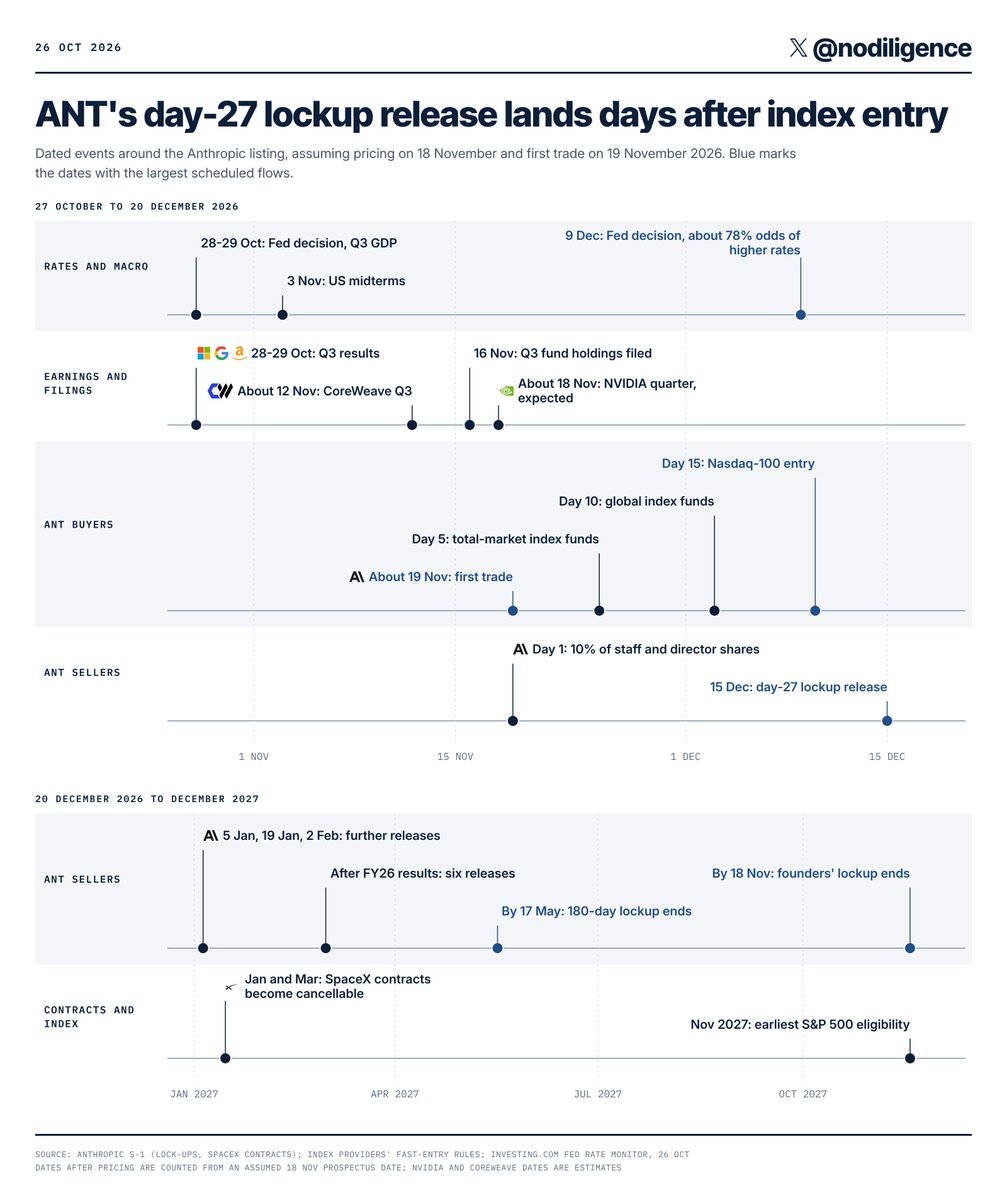
SpaceX is the only listing of this size to compare against. It priced at $135 on 12 June at a $1.77tn valuation, closed day one up about 19%, then dipped below its offer price intraday on 15 July and was at $147.49 on 23 October. Polymarket odds of ANT closing day one above $2tn fell from 74% on 10 September to about 42%, and Reuters reported some investors now value it at about $1.5tn, down from roughly $2tn. If ANT prices on 18 November, index buying arrives on days 5, 10 and 15, the Fed meets on 9 December and the Nasdaq-100 adds it after the close on 10 December. Insider supply starts on day one, when up to 10% of staff and director shares are released, and the day-27 release on 15 December, the first to free shares from the 365-day group too, lands three trading days after the Nasdaq-100 buying.
The best-informed money has been selling or moving up the capital structure
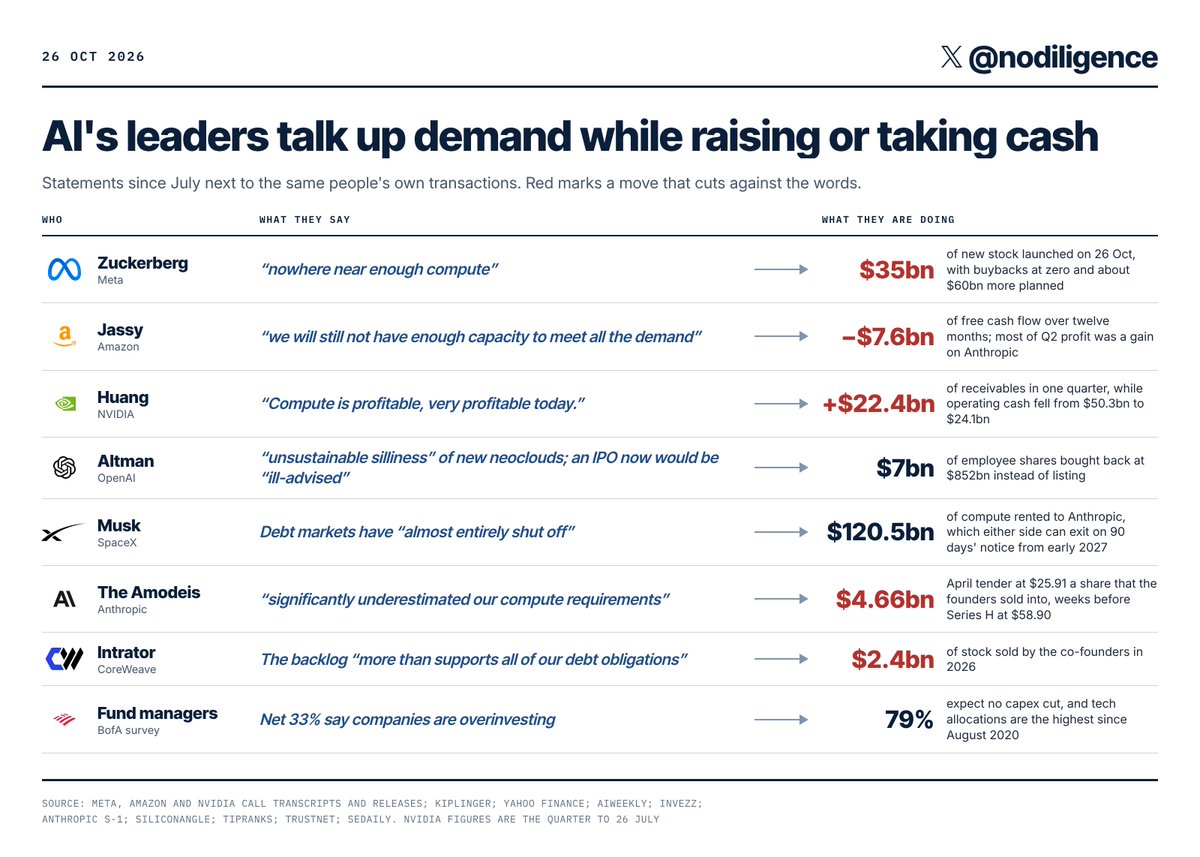
Sources: Meta call; StockAnalysis; NVIDIA call; NVIDIA; Kiplinger; Yahoo Finance; AI Weekly; Invezz; SEC filing; SiliconANGLE; TipRanks; Trustnet; Seoul Economic Daily
The operators all talk about scarcity, and their actions point the other way: stock sales, vendor credit and receivables growing faster than revenue. The Amodeis sold in April at less than half the Series H price, so they gave up money by selling early, and it still means the people with the best view of Claude’s demand chose to take cash before any public price existed. NVIDIA’s numbers matter most here. A supplier with real pricing power gets paid faster, and NVIDIA’s cash conversion halved in a quarter as it borrowed $24.9bn and announced partnerships to mobilise over $500bn of third-party capital for its customers. Its next quarter is expected around 18 November, inside the ANT pricing window.
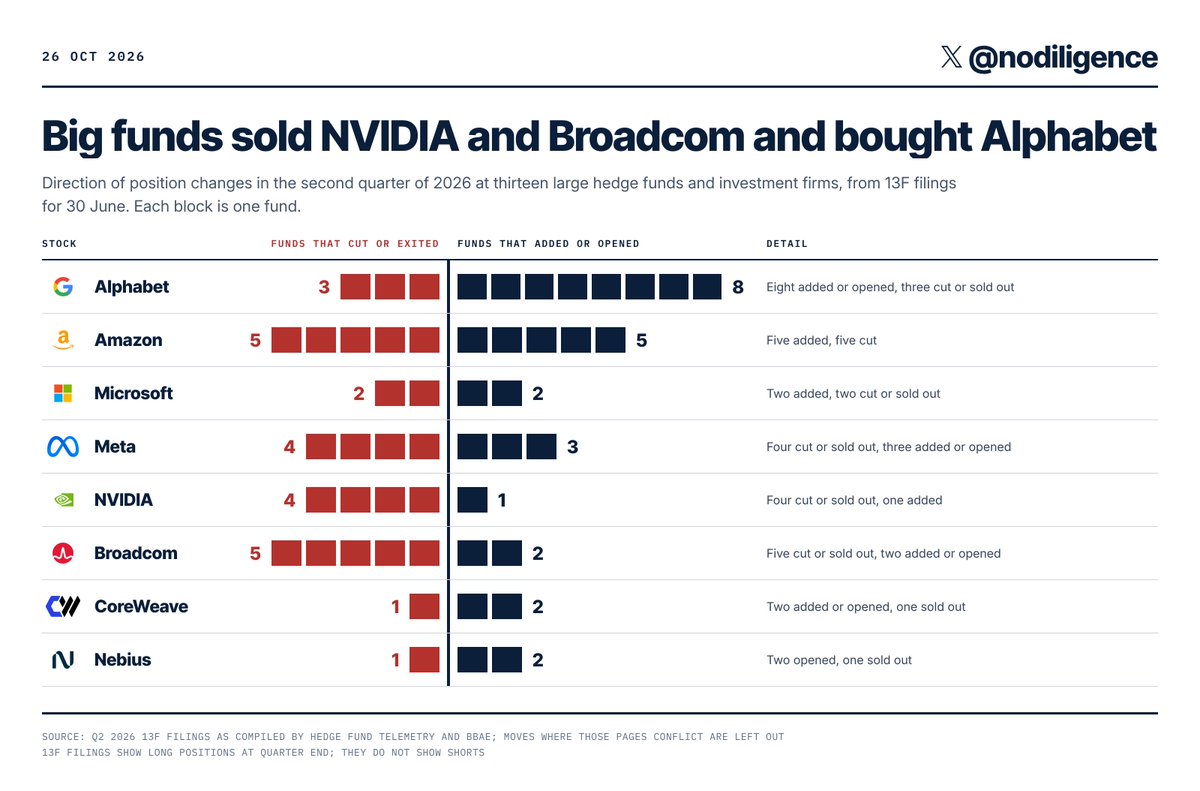
The second-quarter 13F filings show the rotation. Coatue, D1, Tiger and Third Point cut or sold NVIDIA, five of thirteen big funds cut or left Broadcom, and eight added Alphabet, Berkshire Hathaway by about 83%. Altimeter, Coatue and D1 led or co-led Anthropic’s $65bn Series H at $965bn, and all three added Alphabet or Amazon in the same quarter, the two companies whose earnings carry most of the Anthropic mark. They doubled their exposure through stocks they can sell any day. The October BofA survey has bond yields as the top tail risk at 31%, with an AI bubble down to 23%, and semiconductor crowding down from a record 82% in July to 45%. Money has not left AI. It has moved from the suppliers to the balance sheets that pay them, and that works until those balance sheets start issuing stock, which Alphabet did in June, in the same quarter these funds bought it, and Meta began on 26 October. Shorts are concentrated in the most levered layer, with CoreWeave short interest at 23.7% of its free float, and Burry has said the market should “tank hard”to stop the OpenAI and Anthropic IPOs. The third-quarter 13Fs are due on 16 November, because the 45-day deadline falls on a Saturday, days before ANT prices, and will show whether those crossover funds trimmed Amazon and Alphabet ahead of getting direct exposure.
Where the value accrues, and what I would own
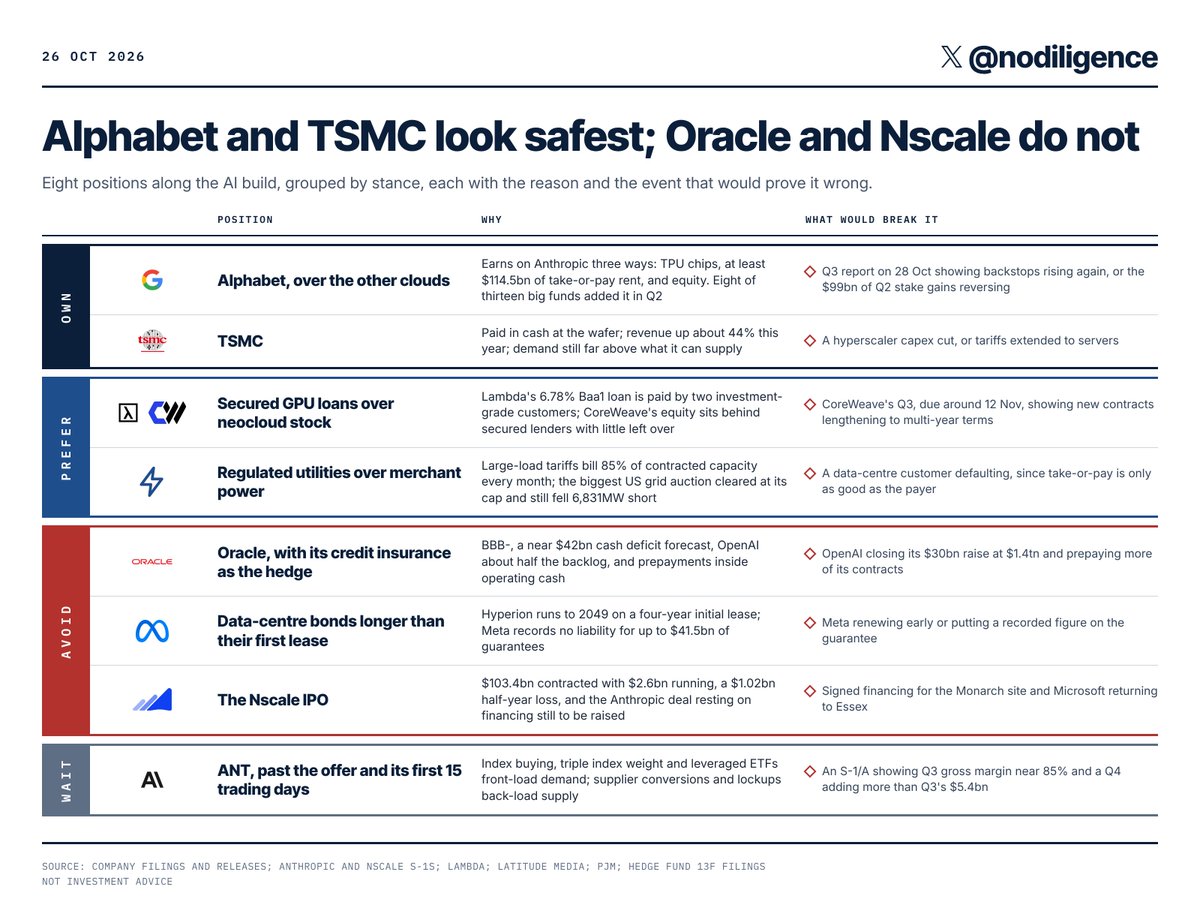
Whoever is paid in cash, up front, on terms shorter than the asset’s life keeps the value. Whoever lends long against short contracts, or takes payment in the customer’s own paper, holds the risk. Hyperscalers push usage risk down to the labs with take-or-pay contracts, construction risk out to neoclouds and bondholders with short leases and value guarantees booked at zero, and price risk back to chip vendors who take notes and stock. The labs push the flexible part of their demand onto the neoclouds. The equity buyers at the end of the chain hold the residual of all of it.
Sources: TSMC; Latitude Media; PJM
Of these, Alphabet is the one I hold with the most conviction, because it sits on the senior side of every Anthropic relationship and still keeps the upside. The weak point is that more than two-thirds of its Q2 earnings per share came from stake gains, and the IPO will set that mark in public. I would size it knowing that an ANT trading below the value Alphabet’s books carry becomes an Alphabet earnings problem in its Q4 2026 results.
The calendar from here
-
28 and 29 October. Alphabet’s backlog (has the $114.5bn Anthropic contract landed, and did the backstop exposure grow again), Microsoft’s backlog growth outside OpenAI, Amazon’s free cash flow, the Fed decision and the Q3 GDP print.
-
Around 12 November, CoreWeave’s Q3. If new contracts are lengthening and interest is falling as a share of revenue, the credit market is too pessimistic and the neocloud layer is a buy.
-
16 November, third-quarter 13Fs. Whether Altimeter, Coatue and D1 trimmed Amazon and Alphabet before ANT lists.
-
NVIDIA’s quarter, expected around 18 November. Receivables growing faster than revenue again would confirm that vendor credit is carrying demand.
-
The S-1 amendment with the price range. Below about 75% gross margin in Q3 would say the first half was flattered by rationed supply, and the blank Run-Rate Revenue as of 31 October should finally be filled in.
-
9 to 15 December. The Fed decision, Nasdaq-100 entry and the day-27 lockup release in one week.
-
January to March 2027. Whether either side gives notice on the SpaceX contracts once they become cancellable, which will show who needs the GPUs more.
-
The start of Broadcom’s draw period. The first quarterly rent paid with notes instead of cash would show the conversion supply beginning.
My mind is still very open on the core thesis but if there is a fall in long yields that reopens the credit window, I will reconsider where things are going. With the 10-year back near 4.5% and the Fed on hold, the build could fund itself with bonds again and the equity issuance would stop looking forced.
Disclaimer
I am doing this independently and sharing it as part of my own research and thinking. The views here are my own and are based on the information available to me at the time. This should not be treated as investment advice or a recommendation to buy, sell, or invest in anything mentioned.
If you have a correction, a better source or a data point I missed, leave it in the comments or send it to me on X at @nodiligence.
沿着这个主题继续读
从一篇文章,找到相关的教程、经验和阅读路径。


